
Wall Street Bets Against Winter (and NatGas) – Remember Jan. 2026?
 Wall Street’s hedge funds have placed their biggest bet against natural gas prices in more than six years. They’re wagering that a “Super El Niño” will give the U.S. a warm, wimpy winter and leave way too much gas sitting in storage. They may be right. But the last time hedge funds loaded up on the short side of gas heading into winter (this past January!), Mother Nature handed them their heads. Read More “Wall Street Bets Against Winter (and NatGas) – Remember Jan. 2026?”
 The feds have spoken: this winter in the Northeast will most likely be warmer than normal, and maybe a little soggier, too. NOAA’s Climate Prediction Center released its official winter outlook last Thursday (Oct. 15), and a “super” El Niño is calling the shots. For those who make a living from Marcellus/Utica gas, a warm winter means less gas burned to heat homes, and that means softer prices. The market noticed. November futures slid 12 cents on Friday. But here’s the twist. In pipeline-starved New England, traders are still betting on $20-plus gas in January. A mild winter can’t fix what bad policy broke.
 Natural gas futures suffered a historic 26% collapse—the steepest one-day percentage drop since 1995 (over 30 years!)—as the most-active “front month” contract plunged over a dollar to close at $3.237/MMBtu. This dramatic retreat was fueled by forecasts of “well above normal” temperatures across the Eastern U.S. and a recovery in production following recent freeze-offs, both of which point toward a looming inventory buildup. Although analysts at NatGasWeather.com suggest the market may have overshot the actual data, the combination of a thawing climate and stabilizing supply clearly spooked investors enough to trigger this record-breaking slide.
 Yesterday, the natural gas price rocketship continued its flight into the stratosphere. U.S. natural gas futures soared Monday, with the front-month contract surging to a three-year high, closing at $6.80/MMBtu, as winter storm Fern swept across the country, driving up heating demand and threatening supply. Spot prices are literally through the roof, spiking to levels we’ve not seen in years. The deep freeze continues through the eastern half of the country at least until Feb. 9, according to NOAA’s temperature outlook. However, there are signs that a “sharp collapse” may soon unfold.
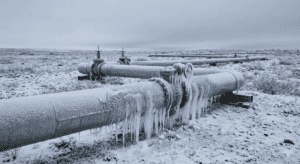 We’ve recently begun to highlight flow restrictions along pipelines that carry Marcellus/Utica molecules. When flows slow or stop (can’t reach other markets), the price typically falls because supply exceeds demand. But sometimes, the opposite happens. If pipelines are restricted due to outages and freeze-offs (as is happening right now with Winter Storm Fern), the supply of natural gas is diminished, leaving insufficient supply to meet increased demand due to the cold weather. When that happens, spot prices for natural gas soar. Wood Mackenzie reported that natural gas freeze-offs across the country reached a single-day high of 17 billion cubic feet (Bcf) on January 25th, approaching the record 18 Bcf set during Winter Storm Uri, as an intense Arctic weather system sweeps across the United States. What about the situation in the M-U?
 As we predicted may happen in a post yesterday, the NYMEX “front month” natural gas futures price closed above $5 yesterday (see
 Old Man Winter has proven once again that he is the one in charge of natural gas prices. A cold blast now entering the Midwest and Northeast, which is moving in until early February (at least), is the reason for a dramatic jump in the NYMEX front-month futures contract price, rising 80.4 cents per MMBtu (26%) in one day, yesterday, to a closing price of $3.9070 MMBtu. It is the largest one-day percentage gain in four years, since January 2022. The price continued climbing this morning (Wednesday) and looks like it might flirt with $5.00!
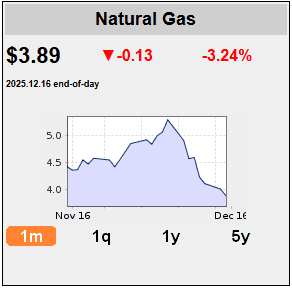 You knew it had to happen. After the meteoric rise of the NYMEX “front month” futures contract from bumping along under $3 just a couple of months ago to hitting a 52-week high of $5.289 on Friday, Dec. 5, 2025, the drop has been almost as rapid. We first crashed back into the $4 range, and as of yesterday, the price sank below $4, closing at $3.8860. The stated reason is a warm weather forecast for the rest of this month. The NOAA Climate Prediction Center (what an oxymoron that is!) shows that the vast majority of the country will experience much warmer-than-average temperatures through Dec. 30.
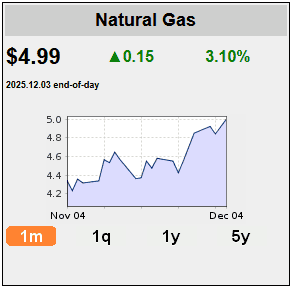 Yesterday, the NYMEX “front-month” futures price for natural gas closed up 15 cents at $4.995 (call it $5), which is the highest closing price for NYMEX in nearly three years (since Dec. 27, 2022). Intraday trading of the front-month contract floated above $5 at points. Weather forecasts of impending frigid weather were the main reason for the increase. Futures prices are now up more than 60% compared with a year ago. “Forecasts for the coldest December since 2010 may tip storage into a deficit by Christmas,” trading firm EBW Analytics wrote in a note to clients. Fewer molecules with more demand equals higher prices. As for the spot price at trading hubs in the Marcellus/Utica region, averaging all of them together, the price closed yesterday at $4.74, nearly at parity with the Henry Hub spot price of $4.87. That’s unheard of!
 Planette, a long-range weather prediction platform that combines cutting-edge AI with decades of Earth system science, says it can predict long-range weather more accurately than others. Planette’s Winter 2025-26 forecast anticipates a highly volatile season driven by a North Pacific dual ocean temperature “blob” and a weakened polar vortex, deeming the current La Niña too weak to be significant. The outlook predicts above-average temperatures interrupted by multiple, predictable, and “significant” cold snaps, with the AI-driven platform offering 30- to 40-day lead times to warn people of their approach. If you’ve been paying attention to MDN’s posts this week, you know how significant weather is in determining the price of natural gas.
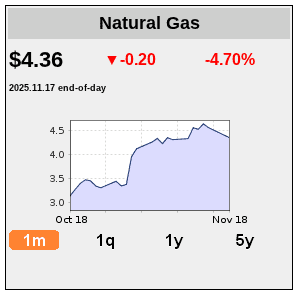 The NYMEX “front month” futures price for natural gas took a dive yesterday, down 20.5 cents (4.5%) in a single day. The price remains firmly in the $4 range, closing at $4.361 per million British thermal units (MMBtus). We thought it would be a good time to check in on the price—what the futures price has been doing, and what the spot/physically traded price in the Marcellus/Utica region has been doing. We can sum up why the price tanked yesterday in a single word: weather. Expanding on that just a bit, NOAA (the National Oceanic and Atmospheric Administration) released its 6-10 Day and 8-14 Day Temperature Outlook graphics yesterday, showing most of the country (in particular the Northeast) will experience warmer than average temperatures for 6-10 days, with the Northeast experiencing warm temperatures all the way through the end of this month and into December.
 The NYMEX futures price for natural gas was a rocket ship over the past two weeks. The NYMEX price closed at $4.1240/MMBtu on Friday, breaking the $4 barrier barely a month after we struggled to break the $3 barrier. In October, the NYMEX front-month contract rose an astounding 82.10 cents per MMBtu, or 25%. In one month! October was the largest one-month gain since August 2022, and the largest one-month percentage gain since February 2025. Zooming out a bit, the NYMEX price was up $1.127 or 38% over the last two months. However, spot prices (at least in the Marcellus/Utica) are more of a mixed bag.
 The front-month NYMEX natural gas futures price soared yesterday (the biggest one-day increase in more than three months), closing up +0.389 (+12.93%) at $3.397/MMBtu. Why? In a word, weather. The price jumped based on forecasts for much colder weather and higher heating demand over the next two weeks than previously expected. Also playing a role is a decline in natural gas output this month and near-record flows of gas to LNG export plants. LSEG (London Stock Exchange Group) said average gas output in the Lower 48 states fell to 106.6 billion cubic feet per day (Bcf/d) so far in October, down from 107.4 Bcf/d in September and a record monthly high of 108.0 Bcf/d in August.