
DNV Raises Long-Term Gas Forecast, Flips N. America to Growth
 DNV, the Norway-based testing, certification, and risk management company, recently released its 10th annual Energy Transition Outlook (ETO). MDN has written about these outlooks before, and they usually read like a slow-motion obituary for fossil fuels. Not so much this year, at least for natural gas. DNV raised its long-term forecast for global gas demand, flipped its forecast for North American gas production from decline to growth, and says the U.S. and Canada are now the world’s biggest gas exporters, “the first time in the modern LNG era.” DNV still predicts gas will lose most of its role in power generation by mid-century, which we take issue with below. Read More “DNV Raises Long-Term Gas Forecast, Flips N. America to Growth”
 A new study from the Boston-based Fiscal Alliance Foundation puts a price tag on what New England’s pipeline shortage costs Massachusetts families. The study, done by Always On Energy Research, finds that Enbridge’s proposed Project Beacon, a 300 MMcf/d (million cubic feet per day) expansion of the Algonquin Gas Transmission pipeline, would have saved Massachusetts ratepayers an average of $367 million per winter over the past seven winters. Even after paying their share of the pipeline’s cost, the average gas-heated household comes out ahead by $76 each winter, and small businesses by $622.
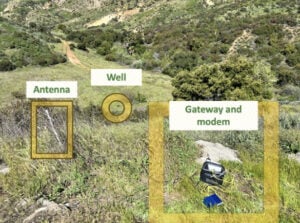 Researchers at the University of Southern California (USC) built a $250 gadget that sits over an old, abandoned oil or gas well and sniffs for methane leaks around the clock, reporting its findings online. The research paper behind it leans on a well-known 2014 Princeton study of abandoned wells in Pennsylvania. That study is worth a second look, because its “average” leaking well isn’t so average. Read the fine print, and you’ll find most old wells leak a tiny amount, or nothing at all, while a handful of bad actors drive the headline numbers. That’s why a cheap tool that can tell the difference could save taxpayers a lot of money.

 The Natural Gas Supply Association (NGSA) released its 26th annual Winter Outlook yesterday, and the bottom line is music to the ears of anyone who pays a heating bill: NGSA sees “downward market pressure” on natural gas prices this winter compared to last. Henry Hub futures for November through March average $3.43 per MMBtu, down $1.08 (23.9%) from $4.51/MMBtu realized last winter. That’s less happy news for landowners hoping for fat royalty checks. But buried on page 5 of the report is a nugget every MDN reader should notice: last winter, while nearly every other U.S. shale basin grew, Marcellus and Utica production actually shrank. The reason? Pipes. Or rather, the lack of them.
 Where do the people who actually drill for, and service, oil and gas wells think the price of natural gas is going? Every three months the Federal Reserve Bank of Dallas asks them, and the answer from the latest survey is: not much higher in the short run, but steadily higher over the next five years. The third-quarter 2026 Dallas Fed Energy Survey, released September 30, found executives expect the Henry Hub price to finish 2026 at $3.29 per MMBtu, rise to $3.82 in two years, and reach $4.28 in five years. Meanwhile, the price in the real world right now is hovering around $3.00. Here’s what the crystal ball says, and what it means for the Marcellus/Utica.
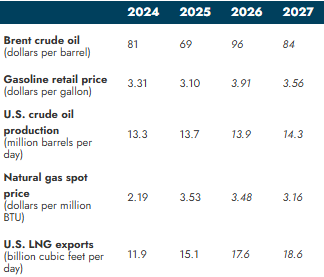
 The U.S. Energy Information Administration (EIA) says U.S. natural gas production hit a new all-time high in July 2026: 137 billion cubic feet per day (Bcf/d) of “gross withdrawals.” That’s great news for the country. But when MDN dug into the state-by-state numbers behind the headline, we found the Marcellus/Utica didn’t help set the record. In fact, Appalachian output dropped in July. The record was made in Texas and New Mexico.
 Every so often the U.S. Energy Information Administration (EIA) publishes something that deserves to be printed out and taped to the wall. This is one of those. To mark America’s 250th, EIA charted the entire history of U.S. energy consumption — from 1776 firewood to 2025 shale gas — and two Pennsylvania milestones show up along the way: Edwin Drake’s first commercial oil well at Titusville in 1859, and the nation’s first full-scale commercial nuclear plant, which came online in the Keystone State in 1957.
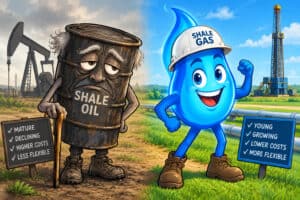 Kimmeridge, the so-called “activist investor” that spent the past year leaning on Coterra Energy (and then Devon Energy) to dump its northeast Pennsylvania Marcellus assets, has just published a sequel to its 2024 “Shale’s Golden Years” white paper. The new paper, “Shale’s Golden Years, Part II: The Cost of Aging,” comes to a conclusion that should make Marcellus/Utica drillers (and landowners) smile: The oil side of shale is aging badly, while the natural gas side remains healthy, abundant, and capital-efficient. The rub? Kimmeridge says gas is so abundant that gas drillers need to move “downstream” to squeeze more value out of each molecule than Henry Hub will pay.
 The Ohio Department of Natural Resources (ODNR) recently released second-quarter 2026 production numbers. The state’s top natural gas producer was Ascent Resources, with 220,554,117 Mcf (220.55 Bcf) produced during the quarter, averaging 2.42 Bcf/d. Ascent’s production accounted for 41% of the state’s natural gas production. The top oil producer in the state, by far, was EOG Resources, which reports under two names: EOG Ohio LLC (the old Encino Energy assets EOG bought last year) and EOG Resources Inc. Together, they produced 8,846,396 barrels of oil during the quarter, which works out to an average of 97,213 barrels per day. That’s 67% (two-thirds!) of Ohio’s entire oil production during 2Q26.
 Remember Synapse Energy Economics? That’s the Massachusetts consulting outfit that, back in 2023, was paid by two Big Green groups to produce a “report” claiming Pennsylvania’s RGGI carbon tax would lower your electric bill (see
 A Syracuse University professor has published a paper in the Journal of the American Planning Association (JAPA) urging towns to treat AI data centers the way they treated fracking a decade ago. Syracuse’s PR department is billing it as “new research” that shows communities how to handle data centers. There’s just one problem. It isn’t really research—by the author’s own admission, no new data was collected. And several of the “facts” about fracking it leans on are flat wrong, especially about Pennsylvania.
 Accounting giant Ernst & Young dropped its annual reserves benchmarking study yesterday, and while the press release leads with oil, the real story for our part of the country is buried in the tables: EQT is now the largest holder of proved natural gas reserves in the United States, and Appalachian-focused producers control roughly a third of all the gas reserves booked by America’s 30 biggest publicly traded drillers.