Antero’s First Dry Gas Pad in 12 Yrs Hits 125 MMcf/d and Won’t Quit
 Antero Resources, the biggest driller in West Virginia and roughly 11% of all Appalachian production, dropped its second quarter 2026 numbers on July 29 and held its analyst call the next morning. Three things jumped off the page: a record quarter, a dry gas well result that borders on spectacular, and a rare public admission that Antero turned down a power deal in its own backyard because the money wasn’t good enough. Read More “Antero’s First Dry Gas Pad in 12 Yrs Hits 125 MMcf/d and Won’t Quit”
 National Fuel Gas Company (NFG) — the Williamsville, NY company that drills (Seneca Resources), pipes (NFG Supply Corporation, Empire), and sells gas at the meter (NFG Distribution Corp) — issued its fiscal third quarter update Wednesday evening and talked it over with analysts Thursday morning. NFG’s fiscal year ends September 30, so their “third quarter” is everyone else’s second quarter (April–June). There’s a lot in here for Marcellus/Utica watchers, but two items stand out: Supply Corporation more than tripled the size of its Line N System Upgrade Project, and Seneca is about to start writing big checks to landowners in Tioga County.
 Expand Energy, the largest natural gas producer in the country, reported its second-quarter 2026 numbers on Tuesday and held its analyst call Wednesday morning. Headline items: net production of 7.48 Bcfe/d (billion cubic feet equivalent per day), net income of $522 million, and a reaffirmed full-year guide of 7.4–7.6 Bcfe/d on $2.75–$2.95 billion of capital spending. But the news that matters most to MDN readers isn’t in the headline — it’s buried in the slide deck. Expand quietly paid roughly $5,000 an acre for 3,000 acres in core Bradford County, Pennsylvania, and turned in the best drilling quarter in the history of its Southwest Appalachia business. Meanwhile, interim CEO Mike Wichterich says the search for a permanent boss is in “the back third” and will land inside the promised nine months. Let’s break it down.
 Infinity Natural Resources, the Morgantown, WV-based operator running Utica Shale acreage in eastern Ohio and stacked dry-gas Marcellus/Utica positions in southwestern Pennsylvania, put out a preliminary hedging update on July 17th, giving the market a first look at its second-quarter derivative results before full Q2 earnings land. We thought that we would take the opportunity to try and explain (decode) what all of this hedging (derivatives) stuff is about. The headline number: a net derivative gain of approximately $57.5 million for the quarter ended June 30, 2026. That figure is a combination of two very different things, and it’s worth separating them.
 Expand Energy, the largest natural gas producer in North America and a giant in the Marcellus/Utica, announced yesterday that it has signed a definitive agreement to buy Twin Eagle Holdings for $1.25 billion in cash from private equity owner Five Point Infrastructure. Twin Eagle is not a driller. It doesn’t own a single well. It’s a physical gas marketer — a middleman that buys gas from producers, moves it through pipelines and storage, and sells it to utilities, power plants, and factories. Twin Eagle markets more than 5 Bcf/d (billion cubic feet per day), controls 44 Bcf (billion cubic feet) of storage and roughly 2 Bcf/d of firm pipeline capacity, and serves over 1,000 customers across the U.S. and Canada. The deal is expected to close in the third quarter. When it does, Expand becomes the country’s biggest gas seller as well as its biggest gas producer.
 The highly functional and responsible Susquehanna River Basin Commission (SRBC), unlike its dysfunctional and irresponsible counterpart, the Delaware River Basin Commission (DRBC), continues to support the shale energy industry by approving water withdrawals and consumptive use requests for responsible, safe shale drilling. The SRBC published a notice in the July 25th Pennsylvania Bulletin that the SRBC approved and/or renewed 21 general water use permits in June for individual shale gas well drilling pads in Clearfield, Lycoming, Sullivan, Susquehanna, Tioga, and Wyoming counties.
 Well, this isn’t what we expected. Bloomberg reported Friday, citing unnamed people “familiar with the matter,” that Devon Energy is exploring a sale of two of its shale positions — the Eagle Ford in South Texas and the Powder River Basin in Wyoming — that together could bring in more than $4 billion. Devon plans to announce a formal strategic review of the two packages when it releases second-quarter results in early August (the release is scheduled for Tuesday, Aug. 4, with the analyst call the next morning). Nothing is final. The timing could slip, and Devon could decide to keep both. Just two weeks ago we told you activist investor Kimmeridge is beating on Devon for moving too slowly on divestitures following the Coterra merger (see
 The Marcellus/Utica region received 26 new drilling permits last week, July 13 – 19, up 19 from two weeks ago (after dipping down 21 three weeks ago). So goes the permitting yo-yo ride. Last week, Pennsylvania issued 23 new permits (after issuing just 1 two weeks ago). Ohio issued 2 new permits. And, West Virginia issued 1 new permit. The drillers who received new permits included: Antero Resources (1), Ascent Resources (2), CNX Resources (2), EQT (1), Expand Energy (3), Formentera Operating (1), Laurel Mountain Energy (5), Pennsylvania General Energy (6), and Range Resources (5).
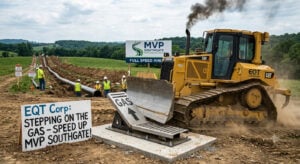 Yesterday, EQT Corporation, the largest Marcellus/Utica-only producer by far, issued its second-quarter 2026 update. We’re pulling out what we consider to be the biggest news from that update for this separate post. During an earnings call with analysts, EQT CEO Toby Rice said that since the Federal Energy Regulatory Commission (FERC) approved the company’s 31-mile Mountain Valley Pipeline (MVP) Southgate project from southern Virginia into northern North Carolina in June (see
 EQT Corporation issued second quarter 2026 results on July 21, followed by an analyst call on July 22. Here’s what matters if you lease acreage to EQT — or own the stock. The company produced more gas using less money in 2Q, raising its estimate of how much it will produce in 2026 by 90 Bcfe to 2,375-2,450 Bcfe (which works out to 6.5 to 6.7 Bcfe/d). As a point of reference, the country’s largest natural gas producer, Expand Energy, is estimating production of 7.5 Bcfe/d in 2026. For landowners leased with EQT with older wells, there’s good news about workovers.
 Range Resources released second quarter 2026 results on July 21 and held its analyst call on July 22. For Marcellus landowners and RRC shareholders alike, there’s a lot packed into this one. Range produced 2.30 Bcfe/d in 2Q26, roughly 67% natural gas, up 5% from a year ago. Of particular note for landowners, Range’s drilling tempo for new wells will slow somewhat during the second half. However, great news for those already drilled. Range is drilling over 50% of its wells on existing pads this year. And, Range drilled a rare Utica well. Does that mean more Utica drilling is on the way for the company?
 Yes, there is a direct connection between the Federal Energy Regulatory Commission’s (FERC) approval of the expansion of an underground salt-dome storage cavern project in Mississippi and the Marcellus/Utica. FERC has approved Leaf River Energy Center’s expansion of its New Home Salt Dome storage facility in Smith, Jasper, and Clarke counties, Mississippi, adding 19.18 Bcf of working gas capacity through new cavern development and facility upgrades. The project includes a new Cavern 5, expansion of Caverns 2 and 4, new compression, and pipeline additions, raising total working gas capacity from 36.0 to 55.18 Bcf.
 We stumbled across an article by East Daley Analytics that is a real eye-opener for us. East Daley analyzed 13 major public G&P (gathering and processing) operators (i.e., pipeline companies). They found that Expand Energy (created by the merger of Chesapeake Energy with Southwestern Energy), with major assets in the Marcellus/Utica and the Louisiana Haynesville, accounts for 52% of DT Midstream’s gathering volumes, 32% of Williams’, and 21% of Energy Transfer’s throughput. Yikes! Just one company.