
DOJ Working from Outdated Info in Evaluating Devon/Coterra Merger
 The proposed $58 billion merger between Devon Energy and Coterra Energy is under scrutiny by the U.S. Department of Justice (DOJ) over “shale market dominance.” The key problem is: how does the DOJ define a “market” that may be dominated? What, exactly, is a market? Critics argue that the DOJ’s narrow market definitions—mirrored in its antitrust case against Visa—ignore broader competitive realities and existing regulations, such as the Durbin Amendment. While the Devon/Coterra merger increases shale concentration, natural gas remains a singular, competitive (much broader) market regardless of extraction methods. By applying outdated antitrust frameworks, the government risks stifling innovation and weakening companies’ ability to compete globally. Ultimately, rational policy must reflect modern market dynamics to avoid economic stagnation and the fragmentation of viable industries. So says author (and lawyer) Daniel Markind. Read More “DOJ Working from Outdated Info in Evaluating Devon/Coterra Merger”
 OTHER U.S. REGIONS: Virtual power plant misinformation in NY; NATIONAL: U.S. natural gas futures post modest gains; AI and the data center backlash; Trump’s war on Iran threatens to drive up oil prices and inflation; Why accounting methods matter in O&G; INTERNATIONAL: Crude jumps as Iran risks mount; The oil glut that never showed up; Iran conflict sends European natgas prices soaring; OPEC+ decides to boost production; War in the Gulf – are there winners and losers?
 The Marcellus/Utica region received a combined 17 new drilling permits last week, Feb. 16 – 22, way down (by 26) from the 43 permits issued two weeks ago. To be fair, 43 permits was one of the highest in recent months, so a slide was expected. What wasn’t expected was that Pennsylvania issued just a single (1) new permit. Ohio issued 8 permits, and West Virginia issued 8 as well. The drillers receiving new permits last week included: Antero Resources, Arsenal Resources, Ascent Resources, Gulfport Energy, and Infinity Natural Resources.
 Coterra Energy issued its fourth quarter and full-year 2025 update yesterday. For this latest update, there was no earnings conference call with analysts due to the impending merger of Coterra into Devon Energy. Companies don’t want to face questions about the merger or risk screwing it up, so they keep mum. Can’t blame them. What we noticed about Coterra’s 4Q update is that the company continues to treat its Marcellus gas production as a cash cow to fund oil drilling in the Permian Basin. Even so, we were encouraged to see an increase in the number of new wells drilled in 4Q and for full-year 2025, although Marcellus production slipped in 4Q and for full-year 2025 relative to 2024. Call it maintenance mode.

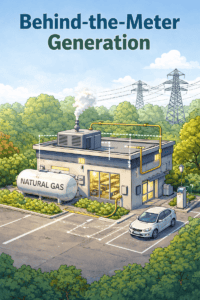 PJM Interconnection recently proposed reforms to its retail BTM (behind-the-meter) generation rules to support data center colocation. The filing, responding to a FERC mandate, introduces a 50-MW threshold for BTM facilities and three new transmission service categories. Under the plan, new loads exceeding 50 MW would be ineligible for “netting,” a process that currently lowers grid charges by balancing on-site generation against consumption. While existing contracts are grandfathered, industrial trade groups warn that removing netting rules threatens the economic viability of combined heat and power facilities, potentially discouraging manufacturing investments while aiming to address regional grid reliability and grid cost-shifting concerns.
 In December, we brought you the sad and unexpected news that Energy Transfer (ET) had suspended development of its Lake Charles LNG project to “focus on allocating capital to its significant backlog of natural gas pipeline infrastructure projects that Energy Transfer believes provide superior risk/return profiles” (see
 Yesterday, the Pennsylvania Independent Fiscal Office (IFO) released its latest quarterly Natural Gas Production Report for October through December 2025 (full copy below). There were 129 new horizontal wells spud (drilled) in 4Q25, a big increase of 46 wells (+55%) compared to 4Q24. Natural gas production volume was 1,934 billion cubic feet (Bcf) in 4Q25 (same as 3Q25), up 63 Bcf (+3.4%) from 1,871 Bcf produced in 4Q24. The average Pennsylvania spot hub price was $3.08, an increase of $1.07 (+53%) from the prior year’s $2.01. All in all, it was a great fourth quarter for the PA Marcellus. The numbers are going in the right direction. However, the big news is annual production.
 Range Resources issued its fourth quarter and full-year 2025 update yesterday. Range’s production averaged 2.24 Bcfe/d in 4Q, approximately 69% natural gas. Range used two rigs and drilled ~225,000 lateral feet across 15 wells during the quarter. 4Q25 drilling and completion expenditures were $167 million. In addition to D&C spending, Range spent approximately $10 million on acreage and $6 million on infrastructure, pneumatic devices, and other investments. For the entire year, Range drilled 69 laterals with an average horizontal length of 14,800 feet, with total activity exceeding 1 million lateral feet drilled.
 Gulfport Energy is the third-largest driller in the Ohio Utica Shale (by the number of wells drilled). Gulfport released its fourth quarter and full-year 2025 update yesterday. The company reports delivering a strong performance during the period, with total net production reaching 1.10 Bcfe per day and net liquids production rising 12% over the fourth quarter of 2024 to 18.2 MBbl per day. Financial highlights included $132.4 million in net income and $234.8 million in adjusted EBITDA, supported by $185.4 million in net cash from operating activities and $120.2 million in adjusted free cash flow. Gulfport spent $25 million on drilling and completions (D&C) and $11.4 million on maintenance, land, and leasehold spending. The company spent an additional $55.7 million on discretionary appraisal and development. Furthermore, the company expanded its footprint through the acquisition of $47.2 million in opportunistic acreage.
 Several Big Green groups, including the Sierra Club, Wild Virginia, Appalachian Voices, and the Center for Biological Diversity, have filed a legal challenge against a permit issued by Virginia for the Mountain Valley Pipeline (MVP) Southgate extension. The Virginia Department of Environmental Quality (DEQ) approved a water permit for the project in January 2026. Big Green radicals argue that the pipeline “threatens” 138 streams, wetlands, and regional drinking water supplies. It’s the typical lawfare tactic used by the left to stall work on projects, hoping to delay them long enough that the builder (EQT in this case) gives up. Or if the builder won’t give up, they have to pay double or triple the price to construct it. That’s the game the radicals are playing.
 METLEN (Greek energy company) and Shell have signed a memorandum of understanding to cooperate on liquefied natural gas (LNG) supply and trading between 2027 and 2031. This partnership allows the Greek company to secure up to one billion cubic meters of LNG annually, leveraging domestic terminals and the Vertical Gas Corridor to supply Central Europe and Ukraine. The agreement highlights Greece’s growing importance as a strategic energy hub designed to replace Russian gas with U.S.-produced alternatives. This shift is further reinforced by increased Mediterranean exploration by major U.S. firms such as Chevron and ExxonMobil, solidifying the region’s role in European energy security. Believe it or not, there are implications for the Marcellus/Utica region.